
01 · Daily briefing
Macro · Crypto · OptionsThe day in markets.
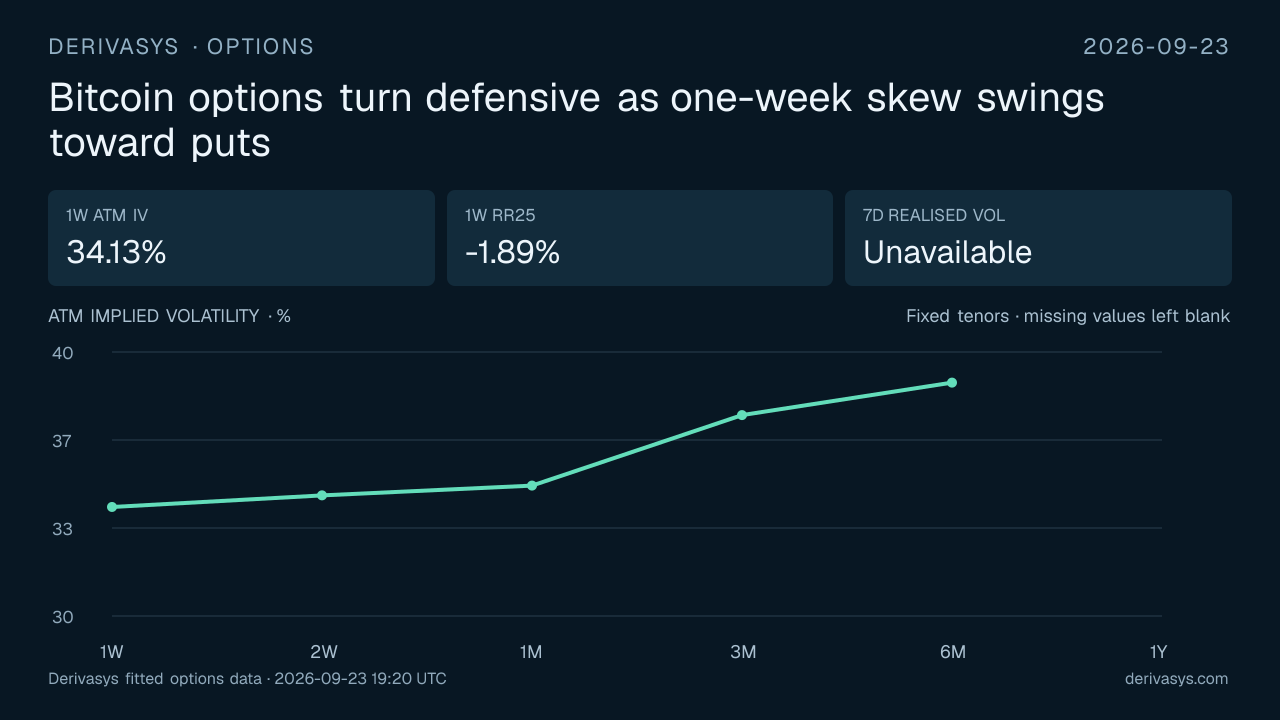
Bitcoin one-week RR25 fell 3.05 volatility points to -1.89%, shifting relative volatility toward puts from a call-rich reading at the prior cutoff. Bitcoin one-week ATM IV fell 2.46 volatility points to 34.13%, while Bitcoin front-end ATM IV across one week to one month averaged 34.55%, down 1.97 points. The Bitcoin 26SEP26 forward price fell 2.53% to $84,426.48. One-minute realised-volatility comparisons were unavailable.
Bitcoin skew shifts toward put protection
Bitcoin one-week RR25 moved sharply lower while front-end ATM IV also declined across standard tenors.
Macro
No qualifying macro context was retained.
Crypto
Bitcoin Magazine reported $999 million of Monday inflows into bitcoin ETFs, citing Farside Investors data.
Links identify the underlying reporting. Events are presented as context, not assigned causes.
BTC volatility context · Derivasys DS30 and Bitfinex BVIV
Model-derived and market-implied volatility.
Derivasys DS30 is model-derived volatility; Bitfinex BVIV is a market-implied reference. Values and their difference are shown in volatility points.
40.33 vol points
Current · 0 min old
38.76 vol points
Current · 1 min old
-1.57 vol points
Available
As of 23 Sept 2026, 19:20 UTC. Derivasys model-free 30-calendar-day implied volatility from fitted BTC SVI slices Bitfinex BVIV reference price from the status channel BVIV minus independently selected latest eligible DS30 at or before the requested cutoff
02 · Options market read
What the volatility surface did.
5 of 6 headline tenors were comparable at both endpoints. The largest ATM IV move was 1W at -2.46 volatility points, to 34.13%.
The intraday RV comparison is unavailable because the one-minute index-return series failed its completeness check. This affects the 24-hour, seven-day and 30-day comparison block.
Derived directly from structured Derivasys surface data03 · Catalyst check
22 Sept 2026, 19:20 UTC to 23 Sept 2026, 19:20 UTCRelevant context found; no confirmed catalyst
Relevant market event
1 relevant event was retained for the comparison window.
News is presented as contextual association unless the structured evidence supports a stronger relationship.
04 · Detailed analysis
What changed across the BTC volatility surface.
Front-end ATM IV decreased, averaging -1.97 volatility points to 34.55% across 1W, 2W and 1M.
Six-month ATM IV was broadly unchanged at 38.84% (-0.49 volatility points); 1Y was unavailable.
RR25 moved towards puts, averaging -1.34 volatility points to -1.28% across the five available headline tenors.
BF25 was broadly unchanged, averaging +0.06 volatility points to 2.11% across the five available headline tenors.
The largest standard-tenor ATM IV move was -2.46 volatility points at 1W, to 34.13%.
Universe roll: added 27SEP26; removed 23SEP26. Comparisons use common expiries only.