
01 · Market read
The day across the three live Derivasys markets.
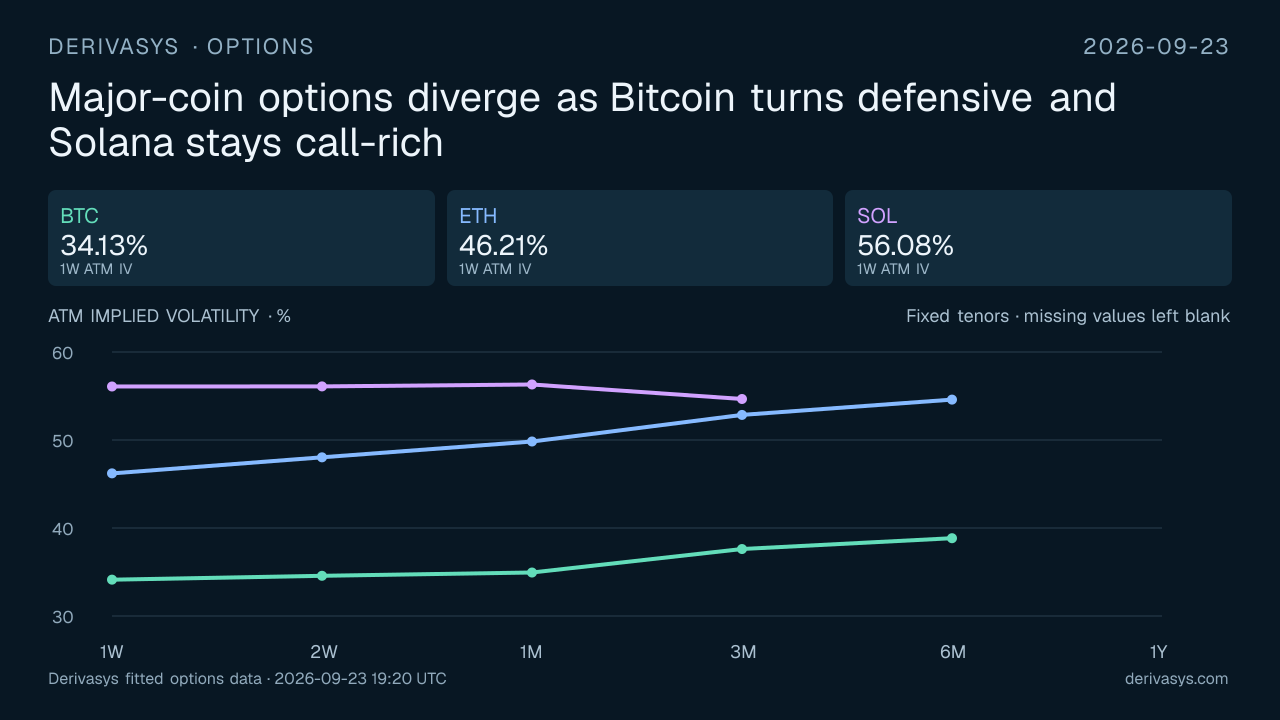
The one-week RR25 gap between Solana and Bitcoin widened to 5.44 volatility points, separating a call-rich Solana surface from a put-rich Bitcoin surface.
This is a comparison, not a pooled surface: each asset keeps its own forwards, expiries, SVI fit and realised-volatility history.
Cross-sectional thesis
Where the complex is diverging.
One-week ATM IV level dispersion is compressing, at +21.95 vol pts; daily one-week ATM IV changes span +2.05 vol pts across the complex.
Comparable implied-versus-realised values are not available for every constituent.
Aligned 24-hour spot correlations: BTC/ETH 0.88 (23 observations).
Historical cross-sectional readings: 1W ATM IV level dispersion 76.0 percentile; Daily 1W ATM IV-change dispersion 28.0 percentile; 1W RR25 dispersion 96.0 percentile.
1W ATM IV change
-1.87 points from the group median
1W ATM IV level
-12.08 points from the group median
1W RR25 level
+4.32 points from the group median
Relative-value rankings
Leaders and laggards across the same cutoff.
| Metric | 1st | 2nd | 3rd |
|---|---|---|---|
| 1W ATM IV level | SOL · 56.08 | ETH · 46.21 | BTC · 34.13 |
| Daily 1W ATM IV change | ETH · -2.28 | BTC · -2.46 | SOL · -4.33 |
| 1W IV minus 7d realised | BTC · unavailable | ETH · unavailable | SOL · unavailable |
| Highest 1W RR25 | SOL · 3.55 | ETH · -0.77 · up 1 | BTC · -1.89 · down 1 |
| Lowest 1W RR25 | BTC · -1.89 · up 1 | ETH · -0.77 · down 1 | SOL · 3.55 |
| 1Y minus 1W curve slope | BTC · unavailable | ETH · unavailable | SOL · unavailable |
| Largest 1Y minus 1W curve change | BTC · unavailable | ETH · unavailable | SOL · unavailable |
| 24h spot performance | BTC · unavailable | ETH · unavailable | SOL · unavailable |
Completed-session cross-asset context
Crypto volatility against VIX and SPX.
The benchmark comparison is separately timestamped to the latest completed US session; it does not replace the intraday crypto surface cutoffs above.
BTC and ETH and SOL 30-day implied volatility remained 2.6–4.0 times VIX, while short-window equity correlations remained mixed.
| Asset | 30d ATM IV | VIX spread | IV / VIX | 20d crypto RV | 20-session SPX RV | RV spread percentile | 30-session correlation |
|---|---|---|---|---|---|---|---|
| BTC | 36.48% | +22.27 vol pts | 2.57× | 48.89% | 10.59% | 80.8 percentile | +0.393 |
| ETH | 49.56% | +35.35 vol pts | 3.49× | 51.19% | 10.59% | 38.1 percentile | +0.277 |
| SOL | 57.26% | +43.05 vol pts | 4.03× | 74.02% | 10.59% | 48.9 percentile | +0.402 |
As of 22 Sept 2026, 20:00 UTC. Crypto RV uses calendar days and sqrt(365); SPX RV uses US sessions and sqrt(252).
03 · Cross-asset scorecard
Implied volatility, realised volatility and skew.
| Asset | Spot 24h | 1W ATM | 1W ATM Δ | 7d RV | 1W IV − 7d RV | 1W RR25 | 1W BF25 |
|---|---|---|---|---|---|---|---|
| BTC | Unavailable | 34.13% | -2.46 vol pts | Unavailable | Unavailable | -1.89 vol pts | +2.15 vol pts |
| ETH | Unavailable | 46.21% | -2.28 vol pts | Unavailable | Unavailable | -0.77 vol pts | +2.95 vol pts |
| SOL | Unavailable | 56.08% | -4.33 vol pts | Unavailable | Unavailable | +3.55 vol pts | +3.89 vol pts |
04 · Term structures
ATM implied volatility across common standard tenors.
| Asset | 1W ATM / Δ | 1M ATM / Δ | 3M ATM / Δ | 6M ATM / Δ |
|---|---|---|---|---|
| BTC | 34.13% / -2.46 | 34.94% / -1.51 | 37.61% / -1.00 | 38.84% / -0.49 |
| ETH | 46.21% / -2.28 | 49.83% / +0.17 | 52.85% / -0.14 | 54.59% / +0.18 |
| SOL | 56.08% / -4.33 | 56.31% / -0.82 | 54.66% / -0.29 | Unavailable |
05 · Constituent evidence
Audit the independently published source artifacts.
23 Sept 2026, 19:20 UTC
Read the BTC report23 Sept 2026, 19:20 UTC
Read the ETH report23 Sept 2026, 19:20 UTC
Read the SOL report06 · Methodology and provenance
A derived publication with no duplicated market data.
The report is assembled at request time from the immutable BTC, ETH and SOL daily-report artifacts for the same UTC report date. It is omitted unless all three exist. Cross-asset averages are descriptive and equal-weighted; no attempt is made to combine distinct volatility surfaces into a single fit.