Daily ETH options market report · 24-hour comparison
Ether options shed three-month convexity premium as volatility eases
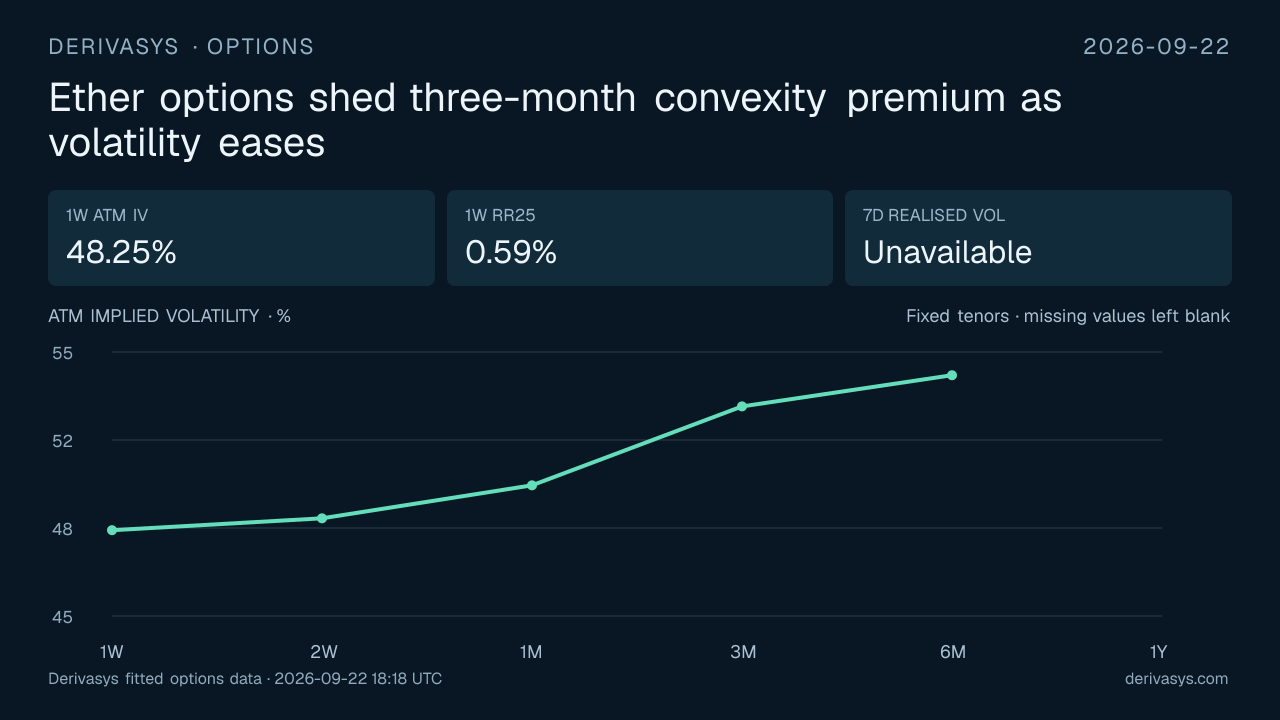
Ether three-month BF25 fell 0.39 volatility points to 2.96% during the observation window, an exceptional move at the 100th percentile of the available 30-day comparison set. The fall reduced the premium in options away from the centre of the distribution. Ether one-week ATM IV also declined 3.02 points to 48.25%, while the nearest eligible forward proxy, 25SEP26, rose 0.20% to $2,757.46 in Derivasys data.
5 of 6 headline tenors were comparable at both endpoints. The largest ATM IV move was 1W at -3.02 volatility points, to 48.25%.
The intraday RV comparison is unavailable because the one-minute index-return series failed its completeness check. This affects the 24-hour, seven-day and 30-day comparison block.
Derived directly from structured Derivasys surface data
03 · Catalyst check
21 Sept 2026, 18:37 UTC to 22 Sept 2026, 18:18 UTC
No catalyst assigned.
No qualifying context was found in the monitored news sources for this reporting window.
04 · Detailed analysis
What changed across the ETH volatility surface.
Front end
Front-end ATM IV decreased, averaging -1.60 volatility points to 48.97% across 1W, 2W and 1M.
Long end
Six-month ATM IV decreased at 54.12% (-1.05 volatility points); 1Y was unavailable.
Skew
RR25 moved towards puts, averaging -0.75 volatility points to 0.66% across the five available headline tenors.
Convexity
BF25 decreased, averaging -0.18 volatility points to 2.89% across the five available headline tenors.
Largest standard-tenor move
The largest standard-tenor ATM IV move was -3.02 volatility points at 1W, to 48.25%.
Universe roll: added 26SEP26; removed 22SEP26. Comparisons use common expiries only.
05 · Standard-tenor ranking
Largest surface events
01
Largest eligible smile rotation
25SEP26, -5.09 vol pts02
Largest standard-tenor ATM IV move
1W, -3.02 vol pts03
Largest standard-tenor RR25 move
2W, -1.21 vol pts04
Largest standard-tenor BF25 move
3M, -0.39 vol pts05
Largest eligible SVI sigma move
25SEP26, -0.1134 param06
Largest eligible SVI rho move
26MAR27, -0.1002 param
06 · ATM volatility
Standard-tenor ATM implied volatility.
Tenor
Current (vol %)
Previous (vol %)
Change (vol pts)
Relative change
1W
48.25
51.27
-3.02 vol pts
-5.89%
2W
48.70
49.92
-1.22 vol pts
-2.44%
1M
49.95
50.50
-0.55 vol pts
-1.09%
3M
52.94
53.39
-0.45 vol pts
-0.84%
6M
54.12
55.17
-1.05 vol pts
-1.90%
9M
55.09
55.42
-0.33 vol pts
-0.60%
1Y
Unavailable
Unavailable
Unavailable
Unavailable
07 · Risk reversals
RR25 skew moved most at 2W.
RR25 moved towards puts, averaging -0.75 volatility points to 0.66% across the five available headline tenors. Negative RR25 denotes a richer 25-delta put wing under the call-minus-put convention.
CurrentPrevious day
Tenor
Current (vol %)
Previous (vol %)
Change (vol pts)
1W
0.59
1.69
-1.10 vol pts
2W
0.67
1.88
-1.21 vol pts
1M
0.52
1.39
-0.87 vol pts
3M
0.42
0.87
-0.45 vol pts
6M
1.12
1.26
-0.14 vol pts
9M
1.81
2.16
-0.35 vol pts
1Y
Unavailable
Unavailable
Unavailable
08 · Butterflies
BF25 convexity changed most at 3M.
BF25 decreased, averaging -0.18 volatility points to 2.89% across the five available headline tenors. BF25 measures the average 25-delta wing premium over ATM IV.
CurrentPrevious day
Tenor
Current (vol %)
Previous (vol %)
Change (vol pts)
1W
2.83
2.89
-0.06 vol pts
2W
2.83
2.94
-0.11 vol pts
1M
2.70
2.81
-0.11 vol pts
3M
2.96
3.35
-0.39 vol pts
6M
3.14
3.36
-0.22 vol pts
9M
2.91
3.14
-0.23 vol pts
1Y
Unavailable
Unavailable
Unavailable
09 · Expiry effects
Near-settlement moves, shown with context.
Contracts with fewer than 2 full days to expiry remain in the tables but are excluded from headline rankings. Settlement proximity, time decay, changing liquidity and fewer quotes can exaggerate their changes.
0.6d
ATM IV change
23SEP26, -5.85 vol pts1.6d
ATM IV change
24SEP26, -4.88 vol pts
10 · Volatility term structure
Today against the previous 24-hour snapshot.
Only fixed tenors bracketed by listed expiries at both snapshots are charted. The listed-expiry table preserves the observable exchange maturities underneath those interpolated points.
CurrentPrevious day
Suppressed outside the observable listed-expiry range: 1Y.
Expiry
Time left
Forward now (USD)
Forward change (USD)
ATM IV now
ATM IV change
RR25 change
BF25 change
23SEP26Expiry effect
0.6 days
2,755.11
+4.61 USD
46.03%
-5.85 vol pts
-1.16 vol pts
-1.04 vol pts
24SEP26Expiry effect
1.6 days
2,756.68
+5.44 USD
48.17%
-4.88 vol pts
-0.75 vol pts
-0.33 vol pts
25SEP26
2.6 days
2,757.46
+5.50 USD
50.13%
-3.30 vol pts
-1.71 vol pts
+0.09 vol pts
2OCT26
9.6 days
2,759.06
+5.48 USD
47.89%
-2.61 vol pts
-1.02 vol pts
-0.18 vol pts
9OCT26
16.6 days
2,761.21
+5.59 USD
48.97%
-0.58 vol pts
-1.31 vol pts
-0.11 vol pts
30OCT26
37.6 days
2,768.18
+5.82 USD
50.19%
-0.60 vol pts
-0.72 vol pts
-0.10 vol pts
27NOV26
65.6 days
2,778.75
+5.30 USD
51.98%
-0.75 vol pts
-0.14 vol pts
-0.32 vol pts
25DEC26
93.6 days
2,789.19
+4.93 USD
53.01%
-0.45 vol pts
-0.47 vol pts
-0.39 vol pts
26MAR27
184.6 days
2,818.55
+7.74 USD
54.14%
-1.06 vol pts
-0.14 vol pts
-0.24 vol pts
25JUN27
275.6 days
2,850.12
+13.47 USD
55.11%
-0.32 vol pts
-0.37 vol pts
-0.23 vol pts
11 · Smile movement
Reconstructed SVI smiles for every common expiry.
Each overlay uses the stored five-parameter SVI fit and the snapshot-specific time to expiry. Ultra-short expiries are displayed but do not determine the headline ranking.
23SEP26rotation towards calls · wing steepening24SEP26wing steepening25SEP26rotation towards puts · wing steepening2OCT26rotation towards puts · wing steepening9OCT26rotation towards puts30OCT26rotation towards puts27NOV26parallel shift lower25DEC26parallel shift lower26MAR27parallel shift lower25JUN27parallel shift lower
Surface movement heatmap
Each cell is the fitted IV change in volatility points. Rows are listed expiries; columns run from the put wing through ATM to the call wing.
IV lowerIV higher
23SEP26
24SEP26
25SEP26
2OCT26
9OCT26
30OCT26
27NOV26
25DEC26
26MAR27
25JUN27
-0.30kATM+0.30k
12 · Technical appendix
Model parameters and normalized Greeks.
These diagnostics preserve the fitted-surface audit trail without competing with the main market story.
Show SVI parameter changes and normalized Greeks
SVI diagnostics
Daily movement in a, b, rho, m and sigma.
Among ranking-eligible expiries, the largest absolute rho change occurred at 26MAR27; the largest sigma change occurred at 25SEP26.
Expiry
Δ a
Δ b
Δ rho
Δ m
Δ sigma
Smile classification
23SEP26
-0.00660
-0.01860
-0.02290
+0.00960
+0.15030
rotation towards calls, wing steepening
24SEP26
+0.03340
-0.02660
+0.06520
+0.04890
-0.11130
wing steepening
25SEP26
+0.02440
-0.01010
+0.00860
+0.02380
-0.11340
rotation towards puts, wing steepening
2OCT26
+0.00870
-0.00820
+0.00490
+0.01630
-0.02620
rotation towards puts, wing steepening
9OCT26
+0.00070
-0.00190
-0.02570
-0.00330
+0.00140
rotation towards puts
30OCT26
+0.00890
-0.01010
+0.00810
+0.02270
-0.01510
rotation towards puts
27NOV26
-0.00450
+0.00080
-0.08940
-0.07480
+0.02270
parallel shift lower
25DEC26
+0.01720
-0.02680
+0.01120
+0.02050
-0.00150
parallel shift lower
26MAR27
-0.01370
+0.01620
-0.10020
-0.09370
+0.00650
parallel shift lower
25JUN27
+0.01630
-0.00700
-0.05060
-0.03310
-0.03260
parallel shift lower
Current surface characteristics
Where normalized model Greek intensity is highest.
These are comparable Black-forward Greeks for a one-ETH ATM-forward call at each listed expiry—not portfolio exposure, open interest or a prediction of dealer positioning.
ETH 30-day implied volatility was 3.4 times VIX, while its 30-session return correlation with SPX was low at 0.28.
Implied-volatility premium
ETH 30-day ATM IV was 51.15%, against VIX at 14.87: a 36.28-point spread and 3.44× ratio.
Daily-close realised-volatility regime
ETH 20-calendar-day realised volatility was 51.50%, versus SPX 20-session realised volatility of 10.66%. The spread ranked at 37.0 percentile of 235 prior observations.
This separate RV estimate uses 20 daily close-to-close log returns, sampled at 16:00 New York time, ending at the completed-session timestamp shown below. It requires a valid close for each day, rather than every intervening minute. Crypto RV is annualised with √365; SPX uses 20 trading-session returns and √252. It does not replace the intraday IV–RV comparison.
Equity co-movement
Return correlation with SPX was 0.276 over 30 aligned sessions and 0.264 over 60 sessions. VIX9D, VIX and VIX3M closed at 13.14, 14.87 and 18.08.
As of 21 Sept 2026, 20:00 UTC. Persisted Derivasys cross-asset context; crypto RV annualizes with sqrt(365), SPX RV with sqrt(252).
13 · Methodology and provenance
Generated from measured Derivasys surface data.
Current snapshot
22 Sept 2026, 18:18 UTC
Comparison snapshot
21 Sept 2026, 18:37 UTC
Source
Derivasys proprietary historical SVI surface database
Comparison window
Nearest successful surface snapshots approximately 24 hours apart
RR convention
25-delta call IV minus 25-delta put IV
BF convention
Average 25-delta wing IV minus ATM forward IV
Fixed tenors
Fixed-tenor measures are published only when listed expiries bracket the target at both comparison snapshots. Targets outside either observable range are suppressed, not extrapolated; headline rankings use only supported tenors.
Smile reconstruction
Listed-expiry smiles are reconstructed from stored SVI total-variance parameters on a fixed log-moneyness grid.
Ultra-short expiries
Expiries with fewer than 2 full days remaining stay in detailed tables but are excluded from headline rankings. Settlement proximity, time decay, changing liquidity and fewer quotes can exaggerate their changes.
Greek normalization
Black forward Greeks for a normalized one-ETH ATM-forward call, zero rate, fitted SVI IV
Catalyst policy
Only sufficiently relevant, reliably sourced events are shown; otherwise no catalyst is assigned.